A Mumbai Western Suburbs redevelopment specialist with 65 projects, ₹763 crore revenue, and a GMP of ₹37 heads to Dalal Street. Here’s the full picture — business model, financials, risks, and the honest apply/avoid verdict.
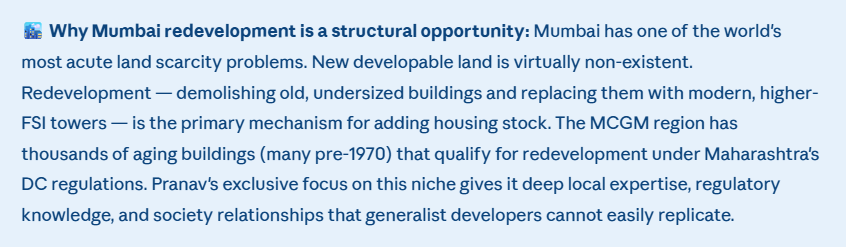
What is Pranav Constructions?
Pranav Constructions Limited is a Mumbai-based real estate developer incorporated in July 2003, focused exclusively on residential redevelopment projects within the Municipal Corporation of Greater Mumbai (MCGM) region — specifically Mumbai’s Western Suburbs. The company has been undertaking redevelopment since 2012 and serves three residential segments: Economical, Mid and Mass-market, and Aspirational housing.
The business model is straightforward but operationally complex: Pranav partners with existing cooperative housing societies — typically old, dilapidated buildings — to demolish and rebuild the structure. Existing tenants receive alternate accommodation and hardship compensation during construction, and the developer retains additional units (known as “saleable area”) beyond what is returned to existing society members. Those additional units, sold in the open market, generate the developer’s profit.
Pranav Constructions IPO snapshot
share
component
India Infra Pvt. Ltd.
investment ₹14,880
(FY26 earnings)
Financials
The company reported revenue of ₹763.93 crore in FY26 against ₹638.24 crore in FY25, and profit of ₹71.32 crore in FY26 against ₹62.25 crore in FY25. That’s 20% revenue growth and 15% PAT growth — a solid performance for a focused regional developer.
| Metric | FY24 | FY25 | FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | — | 638.24 | 763.93 |
| PAT (₹ Cr) | — | 62.25 | 71.32 |
| PAT margin | — | ~9.8% | 9.34% |
| EBITDA margin | — | 15.49% | 17.18% |
| Net worth (₹ Cr) | — | — | 130.83 |
| Total borrowings (₹ Cr) | — | 196.50 | 258.44 |
| Debt-to-equity ratio | — | — | 1.08 |
| Operating cash flow (₹ Cr) | — | — | −41.19 |
| Post-issue P/E | 19.59x (FY26 earnings at upper band) | ||
The EBITDA margin improvement from 15.49% to 17.18% is a meaningful positive — it means the company is getting more efficient at executing its projects. The three concerns that deserve attention are rising debt, elevated D/E, and negative operating cash flow.
Where the IPO money is going
The allocation is sensible and directly tied to the business model. ₹145.72 crore goes toward executing ongoing and upcoming projects — paying for the critical upfront costs (government approvals, FSI purchases, and tenant compensation) that unlock the developable area. ₹91.50 crore goes to debt reduction, which should improve the balance sheet materially post-IPO, bringing the D/E ratio down from 1.08 to a more comfortable level. There is zero OFS excess — the single OFS seller (BioUrja India Infra) exits only ₹35.43 crore worth of shares.
Strengths and Risks — The Balanced View
✅ What works in Pranav’s favour
- Pure-play redevelopment specialist with 10+ years of domain expertise in Mumbai’s Western Suburbs — genuinely deep local knowledge
- Revenue increased 20% and PAT rose 15% in FY26 — consistent growth trajectory
- EBITDA margin expanded from 15.49% to 17.18% — improving project economics
- 65-project pipeline covering 5.01 million sq. ft. provides strong near-term and medium-term revenue visibility
- Capital-efficient model — no outright land acquisition; society partnerships reduce upfront capital commitment
- Post-issue P/E of 19.59x is reasonable for a Mumbai real estate developer with this growth profile
- ₹91.50 Cr of IPO proceeds directly to debt repayment — balance sheet will strengthen materially post-listing
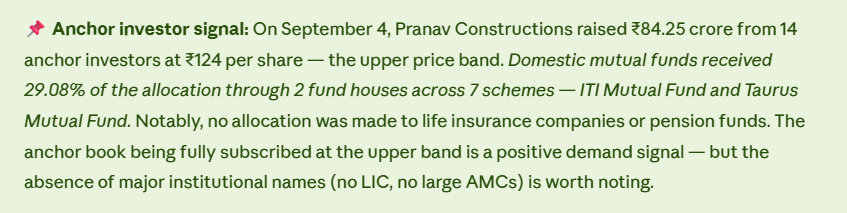
- Anchor book subscribed at ₹124 (upper band) — 14 institutional investors including mutual fund schemes
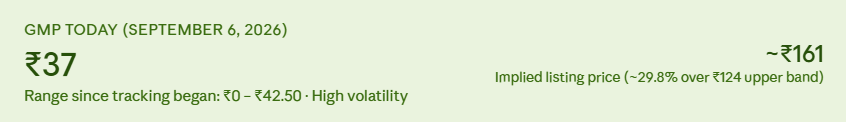
- GMP of ₹37 (~30% implied premium) heading into subscription — strong grey market sentiment
- Retail quota of 45% is higher than the mainboard average, improving allotment probability
⚠️ Risks to understand before applying
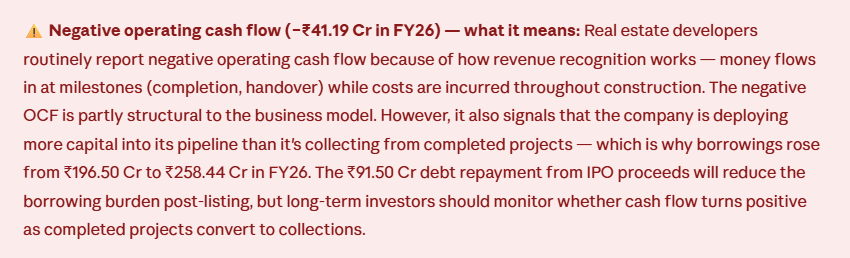
- Negative operating cash flow of −₹41.19 Cr in FY26 — cash conversion from projects must be monitored post-listing
- Borrowings increased from ₹196.50 Cr to ₹258.44 Cr; debt-equity ratio elevated at 1.08 — leverage remains meaningful even after IPO debt repayment
- MCGM region generated 99.70%, 99.69% and 99.50% of revenues in FY26, FY25 and FY24 — near-total geographic concentration; any Mumbai real estate downturn hits the entire business
- Redevelopment projects require successful negotiation with housing societies — disputes, delays, or society disagreements can stall projects
- Inventory risk — failure to sell inventory may have an adverse effect on business and financial performance
- High dependence on government approvals, RERA compliance, and Mumbai’s complex regulatory framework
- Anchor book includes only 2 AMC fund houses (ITI and Taurus) — no tier-1 mutual funds, no LIC, no pension funds
- OFS seller BioUrja India Infra is exiting — worth understanding the reason for this institutional exit
- PAT margin of 9.34% is modest for a real estate business — peers with stronger brands often command higher margins
Key Dates
Bottom Line
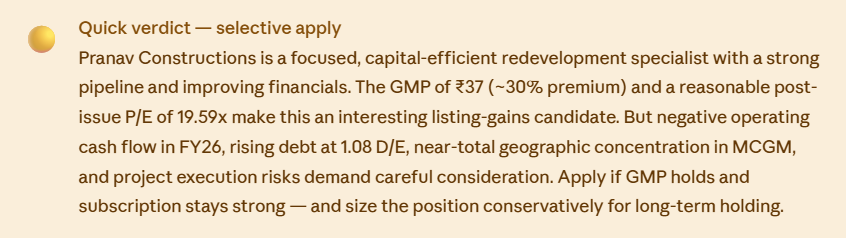
Pranav Constructions is a focused, operationally credible Mumbai redevelopment specialist that has built a genuine competitive position in a structurally undersupplied niche. The 65-project pipeline, 20% revenue growth, EBITDA margin expansion, and reasonable 19.59x post-issue P/E all support a constructive view heading into subscription.
The cautions are equally real: borrowings increased from ₹196.50 crore to ₹258.44 crore and the debt-equity ratio remained elevated at 1.08, operating cash flow was negative in FY26, geographic concentration in MCGM is near-total, and the anchor book’s absence of major institutional names is a caution worth noting. The ₹91.50 crore debt repayment from proceeds improves the near-term picture, but the longer-term investment case depends on successful project execution, positive cash flow conversion, and Mumbai real estate demand holding up.
The practical guidance: watch subscription figures on Day 1 and Day 2 (September 7–8). If QIB subscription exceeds 2× and retail exceeds 5× by Day 2, the listing pop probability is high and the GMP of ₹37 may be conservative. If subscription is muted, reconsider.
Disclaimer: This article is for informational and educational purposes only. Financial figures are sourced from the company’s RHP, Chittorgarh, IPOWatch, Chanakya IPO Thi, Inxits, and other publicly available IPO research. GMP is unofficial, unregulated, and not a reliable indicator of listing performance. This is not investment advice. Please read the full RHP and consult a SEBI-registered financial advisor before applying.
Read More: NSE IPO 2026: India’s Biggest-Ever Listing